
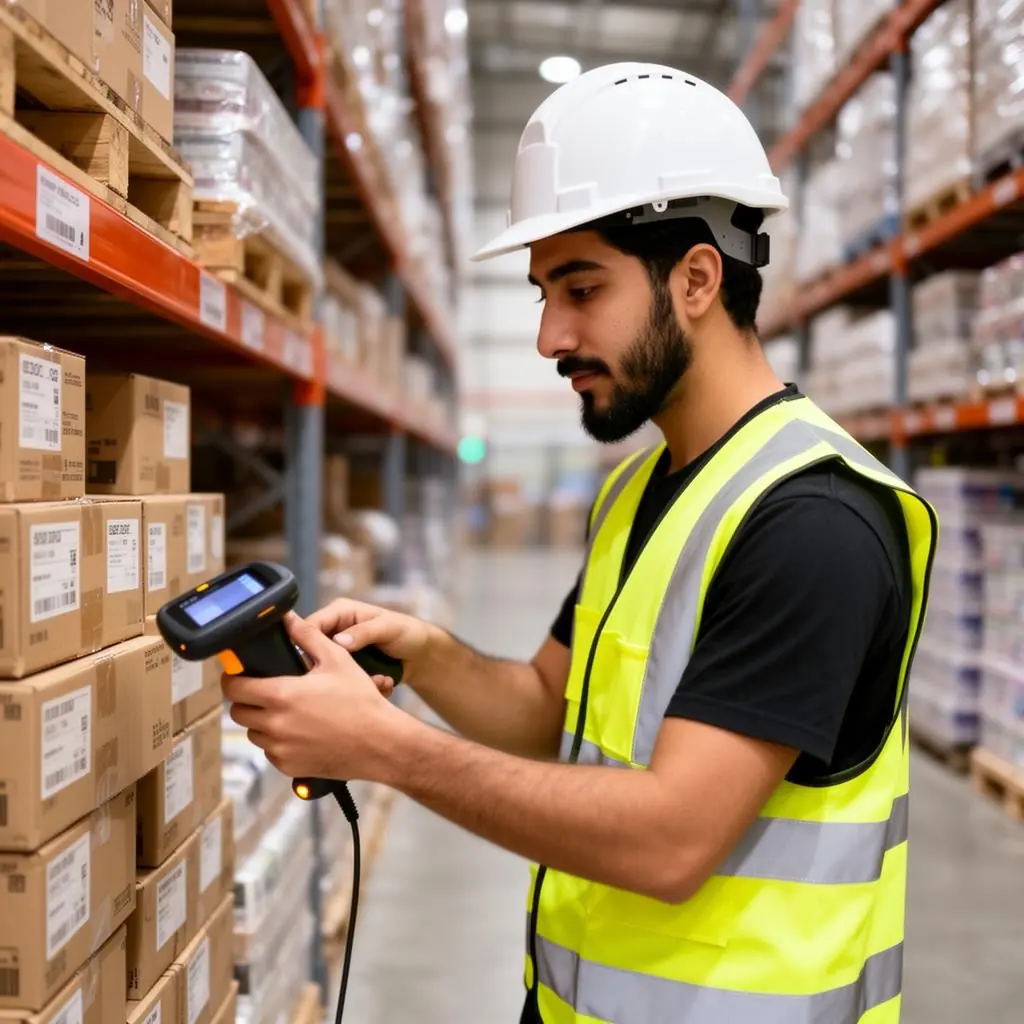

What Is Inventory Shrinkage?
Inventory shrinkage is the gap between the stock your system says you have and the stock that is physically there. If the ERP shows 500 cartons of a product and the count finds 480, the missing 20 are shrinkage. You bought them, paid for them and, in most cases, will never sell them.
Shrinkage is usually expressed as a percentage of sales or of inventory value over a period. For context, the US National Retail Federation's 2023 security survey reported an average shrink rate of 1.6% of sales for US retailers in fiscal 2022, up from 1.4% the year before. That is US retail data, not a Saudi benchmark, and distributors, manufacturers and contractors will see very different patterns. The point is that even a percentage that sounds small is large in money terms. On SAR 50 million of sales, 1.6% is SAR 800,000.
This guide explains where shrinkage comes from, how to measure it properly, the controls that reduce it, the accounting treatment, and how an ERP system supports each step. The worked figures are hypothetical.
Why Shrinkage Costs More Than the Missing Goods
The direct loss is only the first layer. Inaccurate stock records cause a chain of further costs:
- Phantom stock: the system shows items available, so they are not reordered. A customer orders, the picker finds an empty bin, and the sale is lost or delayed.
- Emergency purchasing: gaps discovered late are filled with rush orders, often at higher prices and freight costs.
- Distorted planning: reorder points, safety stock and demand forecasts are built on wrong balances.
- Misstated financials: inventory and gross margin are overstated until the count corrects them, often in one large year-end adjustment.
- Investigation time: staff hours spent searching, recounting and reconciling.
The Main Causes of Shrinkage
It is tempting to assume shrinkage means theft. Theft is real, but in many warehouses a large share of variances comes from process errors that have no bad intent behind them. Treating every variance as theft damages trust and misses the easier fixes.
1. Process and recording errors
- Receiving without counting: the storekeeper records the purchase order quantity rather than what actually arrived. A supplier sends 480 units, the system records 500.
- Unit of measure confusion: goods bought in cartons of 12 and sold by the piece. If 100 cartons are recorded as 100 pieces, 1,100 pieces vanish from the books; if the reverse happens, phantom stock appears.
- Picking errors: the picker sends 12 instead of 10. The system deducts 10; the shelf loses 12.
- Unrecorded returns: goods come back from a customer or a sales van but no return document is created.
- Transfers in limbo: stock leaves one warehouse and is not received at the other for days. If a count happens in between, it looks like a loss.
- Unrecorded consumption: samples, internal use, or materials issued to production without an issue document.
2. Internal theft and fraud
Employees with access to both stock and records can remove goods and hide the gap, for example by recording false damage, creating fictitious returns, or adjusting balances directly. The risk is highest where one person can receive, store, adjust and count without anyone else checking.
3. External theft
Shoplifting in retail branches, theft from vehicles or yards, and supplier short-shipments that are signed for without checking all fall here.
4. Damage, spoilage and expiry
Goods broken in handling, spoiled through poor storage or heat, or expired on the shelf are a real loss. They become shrinkage when they are thrown away without being recorded.
Where Shrinkage Hides in Different Businesses
The causes above apply everywhere, but each type of business has its own weak spots.
Retail branches
External theft, cashier errors and price overrides are the familiar risks. Less obvious are items sold under the wrong barcode, which leaves one item showing a surplus and another a shortage, and goods moved between branches informally to cover a customer request. Linking POS sales directly to inventory and requiring a transfer document for every branch-to-branch movement closes most of these gaps.
Distributors with van sales
Each sales van is a small mobile warehouse. Stock loaded in the morning, sold, returned or damaged during the day must be reconciled every evening. When vans are reconciled weekly instead of daily, variances become impossible to trace to a specific day or customer.
Contractors and project site stores
Materials delivered directly to site, issued to subcontractors or moved between projects are a common source of loss. Treat each site store as a warehouse location, record issues against the project and cost code, and count high-value materials such as cable and copper pipe more often than bulk items.
Manufacturers
In factories, shrinkage often sits in work in progress: materials issued in excess of the bill of materials, scrap that is not reported, and yields lower than standard. Comparing actual consumption with the BOM for each production order shows where material is really going.
Measuring Shrinkage Properly
You cannot reduce what you do not measure consistently. A practical approach:
- Calculate it by period: shrinkage value equals book inventory at cost minus counted inventory at cost, after all documents for the period are posted.
- Express it as a rate: shrinkage value divided by sales for the period, or by average inventory value, used consistently.
- Break it down: by warehouse, branch, category, item and reason code. A single company-wide figure tells you almost nothing about where to act.
- Separate known from unknown loss: recorded damage and expiry are known losses. Unexplained count variances are unknown losses. Both matter, but they need different responses.
A hypothetical example
A distributor with three warehouses runs its quarterly count. Total book inventory at cost is SAR 6.2 million, and counted inventory is SAR 6.08 million, a variance of SAR 120,000. Broken down, Warehouse A accounts for SAR 15,000, Warehouse B for SAR 22,000 and Warehouse C for SAR 83,000. Within Warehouse C, two categories sold by the piece but bought by the carton account for SAR 61,000. The investigation finds a unit of measure setup error on four items, not theft. Correcting the conversion factors and retraining receivers removes most of the variance at the next count.
Controls That Reduce Shrinkage
Scan every movement
Require barcode scanning at receiving, putaway, picking, transfers and returns. Scanning removes most keying errors and records who did what and when. It also makes unit of measure explicit, because each barcode is tied to a specific pack size.
Blind receiving
Let receivers count what arrived without seeing the expected quantity, then compare with the purchase order in the system. Differences are flagged before the delivery note is signed.
Cycle counting instead of one annual count
Counting a portion of items every week, with high-value or high-risk items counted more often, finds errors while they are still traceable. An ABC approach is common: A items monthly, B items quarterly, C items twice a year. Our guide to stocktaking explains how to organise both full counts and cycle counts.
Segregation of duties
The person who receives goods should not also approve inventory adjustments, and counts should be done or verified by someone who does not manage that location's stock. In a small business where full separation is impossible, add review: adjustments above a set value require a second approver.
Reason codes and approval for adjustments
Every stock adjustment should carry a reason, such as damage, expiry, count variance or sample, and adjustments above a threshold should need approval. A list of adjustments by user and reason is one of the most useful fraud detection reports you can run.
Batch and expiry control
For food, pharmaceuticals and chemicals, tracking batches and expiry dates and picking by first-expiry-first-out reduces write-offs. Items approaching expiry can be flagged for promotion or return to supplier while they still have value. See our article on batch tracking for more.
Physical security
Restricted access to high-value cages, controlled exits, CCTV in receiving and dispatch areas, and sealed transfer vehicles all help. Physical measures work best when combined with system controls, so a missing pallet can be traced to a specific transaction and time.
Exception reports
Set alerts for patterns worth investigating: frequent negative stock on the same items, repeated adjustments by one user, returns without a matching sale, or transfers open longer than a set number of days.
Controls by Cause
| Cause | Main control | Supporting report |
|---|---|---|
| Receiving errors | Blind receiving with scanning | Received versus ordered by supplier |
| Unit of measure errors | Defined conversions per item and barcode per pack size | Variances on multi-unit items |
| Picking errors | Scan-to-pick and pack check | Customer short or over shipment claims |
| Unrecorded returns | Return document linked to original invoice | Returns without a source document |
| Transfer gaps | In-transit location with receipt confirmation | Open transfers by age |
| Internal theft | Segregation of duties and adjustment approvals | Adjustments by user and reason |
| Expiry and damage | Batch and expiry tracking, FEFO picking | Items nearing expiry; write-offs by reason |
Accounting for Shrinkage
When a count confirms a shortage, the adjustment reduces inventory and records an expense, typically through an inventory loss or shrinkage account that rolls into cost of sales. For example, a confirmed SAR 120,000 shortage is recorded as a debit to inventory shrinkage expense and a credit to inventory of SAR 120,000. Posting shrinkage to its own account, rather than burying it in cost of goods sold, keeps it visible to management.
Separately, IAS 2 requires inventories to be measured at the lower of cost and net realisable value. Damaged, obsolete or near-expiry stock that is still on hand may need a write-down even if it is not missing. Saudi companies following IFRS as endorsed by SOCPA apply this standard. Retention also matters: the Commercial Books Law requires end-of-year inventory to be recorded and records retained for ten years, although a new Commercial Transactions Law approved in October 2026 will replace it once in force, so check the current requirements with your auditor.
A 12-Week Shrinkage Reduction Plan
| Weeks | Action |
|---|---|
| 1 to 2 | Full count of the highest-variance location; set a clean baseline |
| 3 to 4 | Review unit of measure setups and barcodes for top items; fix conversion errors |
| 5 to 6 | Introduce blind receiving and scan-based picking in the pilot warehouse |
| 7 to 8 | Set reason codes and approval thresholds for adjustments; start weekly exception review |
| 9 to 10 | Launch ABC cycle counting schedule |
| 11 to 12 | Compare variance to baseline; roll out to remaining locations |
Common Mistakes
- Waiting for the annual count to discover problems that are months old.
- Letting the same person receive, adjust and count stock.
- Allowing adjustments without reasons or approvals.
- Blaming theft before checking unit of measure setups and receiving practices.
- Writing off damaged goods physically but not in the system, or the reverse.
How Tranquil ERP Helps
Tranquil's inventory module supports central inventory across locations and multiple units of measure per item, and it shares data with purchasing, sales, POS and financial accounting, so receipts, issues, returns and adjustments post to the ledger without re-keying. Barcode integration is available on the manufacturing side, and customisation services can add approval steps and reports such as adjustments by user. See the inventory management page, and our guide to inventory control systems for the wider control framework. To review your current stock controls, contact the Tranquil team.
Frequently Asked Questions
What is a normal shrinkage rate?
There is no single normal rate. The NRF reported 1.6% of sales for US retailers in fiscal 2022, but distributors, manufacturers and Saudi retailers will differ. The useful benchmark is your own trend by location and category over time.
Is shrinkage always theft?
No. Receiving errors, unit of measure mistakes, unrecorded returns and transfers, and damage that was never written off are common causes. Check processes and system setup before assuming theft.
How often should we count stock?
A full count at least once a year, plus cycle counts during the year. High-value or fast-moving items are often counted monthly, others quarterly or twice a year.
How is shrinkage recorded in the accounts?
The confirmed shortage reduces inventory and is charged to an expense account, usually shrinkage or inventory loss, which forms part of cost of sales. Keeping it in its own account makes it easier to monitor.
Can an ERP stop shrinkage completely?
No system removes it entirely. An ERP reduces it by enforcing scanning, approvals and segregation of duties, and by showing exceptions early enough to investigate them.